 https://xanderia.com/wp-content/uploads/2026/09/Emergency-Fund-or-SInking-Fund-Bm.jpeg
423
1024
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-09-30 02:47:132026-09-30 02:50:31Emergency Fund vs Sinking Fund: Many Still Get Confused — Which Savings Is For What?
Your car suddenly breaks down and you need RM1,000 for repairs.
At the same time, you already know your road tax and car insurance are due in two months — also around RM1,000.
Both require money. But should both come from the same savings?
Actually, no.
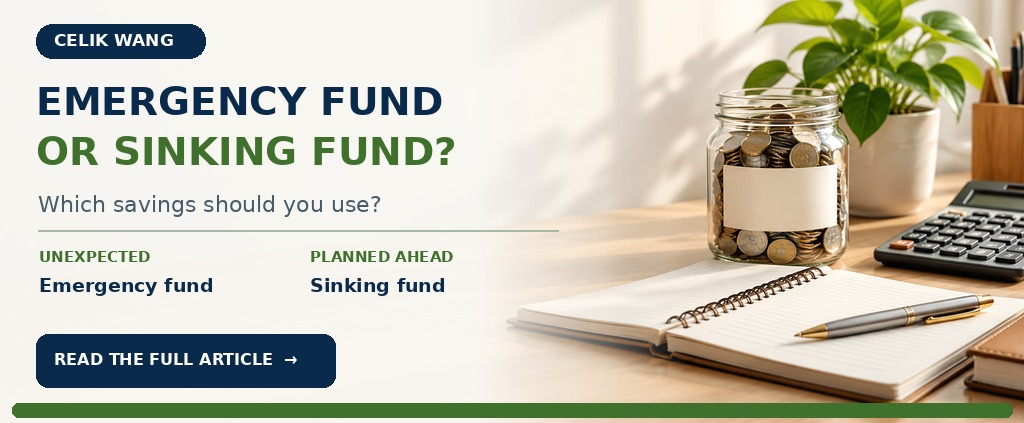
This is where understanding the difference between an Emergency Fund and a Sinking Fund becomes important.
Many of us do save, but all our savings are often kept in one place. When festive seasons, car servicing, school expenses or annual insurance payments come around, we start dipping into that same pool of money.
Then, when a real emergency happens, our savings may already be reduced.
Emergency Fund: For Things You Did Not Expect
An Emergency Fund is money set aside specifically for situations that happen suddenly and require immediate attention.
For example:
- Unexpected car repairs
- Loss of job or income
- Urgent home repairs
- Unexpected family needs
Simply put, an Emergency Fund is your financial “umbrella” when something unplanned happens.
That is why it should ideally not be used for holidays, a new phone or yearly expenses that can actually be anticipated.
Sinking Fund: For Things You Know Are Coming
The term Sinking Fund may sound technical, but the concept is simple.
It is money that you save little by little for a specific future expense that you already know is coming.
For example, your car insurance and road tax cost RM1,200 a year.
Instead of scrambling to find RM1,200 when the payment is due, you can save:
RM1,200 ÷ 12 months = RM100 per month
That RM100 goes into a Sinking Fund specifically for your car.
The same method can be used for:
- School expenses
- Festive seasons
- Trips back to your hometown
- Car servicing
- Family holidays
- Annual takaful or insurance payments
These expenses may feel like “emergencies” when the time comes. But in reality, we already knew they were coming.
The difference is whether we prepared for them or not.
So, Which One Should You Prioritise?
If you do not have either fund yet, you do not need to wait until you have a large amount of extra money.
Start small.
For example, if you can save RM200 a month:
RM120 → Emergency Fund
RM80 → Sinking Fund
As your financial position improves, you can gradually increase the amount.
You also do not necessarily need to open many separate bank accounts. If your banking app has features such as Goals, Pockets or savings jars, you can use them to separate your money by purpose.
What matters is knowing which money can be used and which money should not be touched.
Ask Yourself This Before Using Your Savings
Before taking money from your Emergency Fund, ask:
“Was this expense truly unexpected?”
If your road tax expires every year, it is not an emergency.
If festive celebrations happen every year, that is not an emergency either.
If you already know your tyres may need replacing in a few months, start building a Sinking Fund now.
The more expenses we can anticipate and prepare for, the less likely we are to disturb our Emergency Fund.
So, remember this simple rule:
An Emergency Fund is for things you DON’T KNOW will happen.
A Sinking Fund is for things you KNOW will happen.
Both are savings, but they serve very different purposes.
When every ringgit has a purpose, we are not just “saving money” — we are building a financial life that is more prepared, organised and less stressful.
https://xanderia.com/wp-content/uploads/2026/09/Emergency-Fund-or-SInking-Fund-Bm.jpeg
423
1024
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-09-30 02:47:132026-09-30 02:50:31Emergency Fund vs Sinking Fund: Many Still Get Confused — Which Savings Is For What? https://xanderia.com/wp-content/uploads/2026/08/WhatsApp-Image-2026-08-18-at-15.12.43-Eng.jpeg
660
1600
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-08-18 08:10:212026-08-18 08:10:21PayLater, Credit Card or Personal Financing: Which One Should You Choose?
 https://xanderia.com/wp-content/uploads/2026/08/IMG-20260814-WA0191-e1787021591326.jpg
1442
2112
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-08-18 02:54:102026-08-18 03:50:39Perhimpunan Penjawat Awam dan Pelancaran Kibar Jalur Gemilang Peringkat Negeri Sembilan 2026
 https://xanderia.com/wp-content/uploads/2026/07/ChatGPT-Image-Jul-29-2026-04_10_27-PM-1.png
807
1949
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-07-31 08:37:152026-07-31 09:17:26Financial Literacy: Why Building an Emergency Fund Should Come Before Financing
 https://xanderia.com/wp-content/uploads/2026/03/WhatsApp-Image-2026-03-10-at-4.04.43-PM.jpeg
960
1280
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-03-14 08:58:582026-06-15 03:28:41Kembara Prihatin Negeri Sembilan: Xanderia Menyantuni Penjawat Awam Sempena Bulan Ramadhan
 https://xanderia.com/wp-content/uploads/2025/07/woman-working-late-project-scaled.jpg
1707
2560
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2025-07-22 01:32:582025-07-22 01:32:58Realiti Wang di Malaysia: 7 daripada 10 Dewasa Terlalu Hampir Dengan Masalah Kewangan—Apa Yang Anda Boleh Buat Sekarang
 https://xanderia.com/wp-content/uploads/2025/06/fantasy-scene-wealth-scaled.jpg
1707
2560
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2025-06-24 09:26:402025-06-24 09:32:54Hati-Hati! Jenis-Jenis Skim Cepat Kaya Yang Sasar Penjawat Awam
 https://xanderia.com/wp-content/uploads/2025/06/young-man-delivering-package-customer-home-delivery-scaled.jpg
1707
2560
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2025-06-18 09:03:352025-06-18 09:03:35Semakin Ramai Rakyat Malaysia Terpedaya dengan Penipuan Bungkusan: Jangan Bayar untuk Barang yang Tak Pernah Anda Tempah
 https://xanderia.com/wp-content/uploads/2025/05/3d-cartoon-portrait-person-practicing-law-related-profession-scaled.jpg
1435
2560
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2025-05-20 04:09:102025-05-20 04:10:10Kewangan Teratur, Hidup Lebih Tenang: Panduan Literasi Kewangan untuk Penjawat Awam