 https://xanderia.com/wp-content/uploads/2026/10/Persaraan-ENG.jpeg
900
1600
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
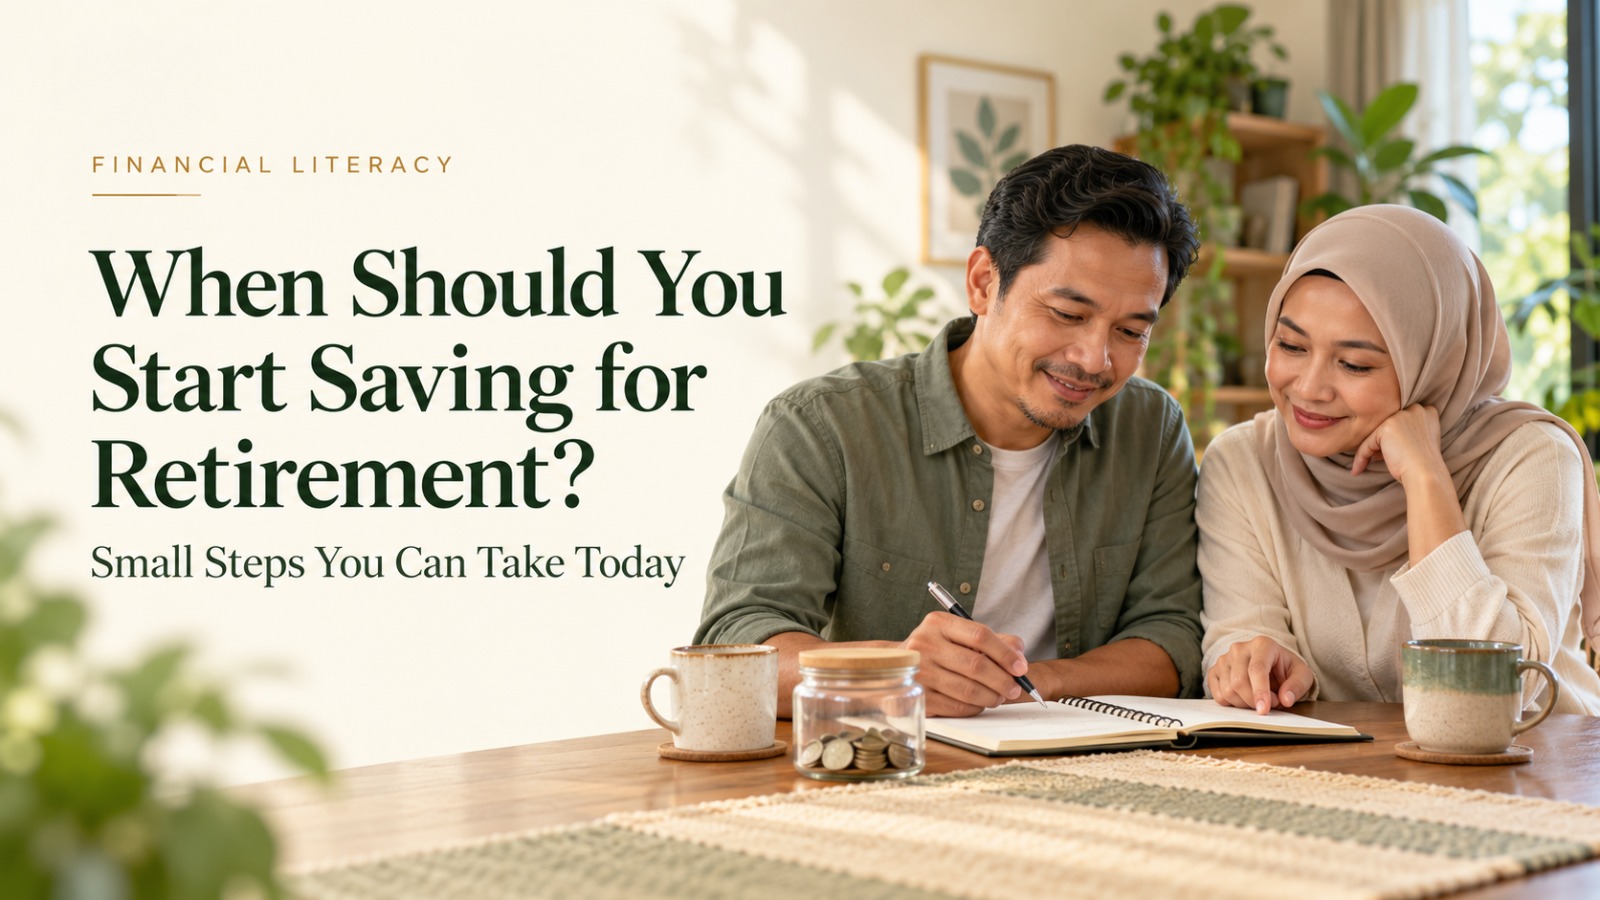
Haryth Singularity2026-10-22 02:17:122026-10-22 02:17:12When Should You Start Saving for Retirement?
Small Steps You Can Take Today
“I’ll start saving when I get a pay rise.”
Then the pay rise arrives, along with new expenses. Your child starts school, the car needs repairs and your parents need financial support. Retirement savings keep waiting their turn.
Before you realise it, “later” has become several years.
So, when should you begin? As early as you can afford to, even with a small amount. If you have not started, today is still an opportunity to take the first step.
Picture Life After Your Last Working Day
No morning commute. More time with family, a favourite hobby or a leisurely breakfast without checking the clock. But groceries, electricity bills and healthcare expenses will continue.
Ask yourself: “What kind of life would I like when I stop working, and how will I pay for it?”
For civil servants, whether you are under a pension scheme or EPF, understanding your own retirement income is an important starting point. Review your estimated benefits or savings and compare them with your expected living needs.
1. Start with an Amount You Can Maintain
You do not have to wait until you can save hundreds of ringgit. If your budget allows, begin with RM50 or RM100 a month. It may feel modest, but it establishes the habit of setting money aside for your future.
Choose an amount that leaves room for essential needs and required repayments. Increase it gradually as your circumstances improve.
2. Make Saving Part of Payday
Have you ever planned to save whatever remained at the end of the month, only to find there was nothing left? Try setting aside your savings when your salary arrives. An automatic transfer to a separate account can help. This gives saving a regular place in your monthly budget.
3. Make Use of Commitments That End
Finishing your car repayments can bring a welcome sense of relief. Before committing the entire amount to another purchase, consider redirecting part of it towards retirement savings. You can take the same approach when you receive a pay rise.
There is room to enjoy your income while also preparing for your future needs.
4. Build an Emergency Buffer Alongside It
An unexpected car repair or urgent family expense can interrupt your savings plans. Gradually build an emergency fund that you can access easily. This can reduce the need to use retirement savings or take on additional debt when something unexpected happens.
What If You Are Already in Your 40s or 50s
Start with where you are today. Review your savings, outstanding debts and the time remaining before retirement. Then choose steps you can maintain consistently.
Avoid taking investment risks you do not understand simply because you feel you need to catch up. Retirement may feel distant, but today’s small decisions shape how prepared you will be.
On your next payday, set aside an amount you can afford for your future. Your retirement-age self will appreciate that first step.
https://xanderia.com/wp-content/uploads/2026/10/Persaraan-ENG.jpeg
900
1600
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-10-22 02:17:122026-10-22 02:17:12When Should You Start Saving for Retirement? https://xanderia.com/wp-content/uploads/2026/10/Generasi-Sandwich-ENG.jpeg
900
1600
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-10-19 03:59:422026-10-19 03:59:42The Sandwich Generation: Managing Money While Supporting Parents, Children and Yourself
 https://xanderia.com/wp-content/uploads/2026/10/Aset-Liabiliti-ENG.jpeg
900
1600
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-10-16 08:45:202026-10-16 08:49:27Assets vs Liabilities: Are You Getting Wealthier or Taking on More Commitments?
 https://xanderia.com/wp-content/uploads/2026/10/Medical-Cards-EN.jpeg
900
1600
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-10-05 09:35:092026-10-05 09:48:40Medical Cards, Life Takaful and Personal Accident Coverage: What’s the Difference, and Which Do You Need?
 https://xanderia.com/wp-content/uploads/2026/09/Emergency-Fund-or-SInking-Fund-Bm.jpeg
423
1024
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-09-30 02:47:132026-09-30 02:50:31Emergency Fund vs Sinking Fund: Many Still Get Confused — Which Savings Is For What?
 https://xanderia.com/wp-content/uploads/2026/08/WhatsApp-Image-2026-08-18-at-15.12.43-Eng.jpeg
660
1600
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
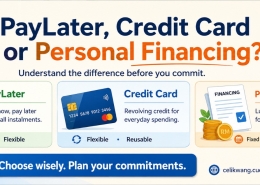
Haryth Singularity2026-08-18 08:10:212026-08-18 08:10:21PayLater, Credit Card or Personal Financing: Which One Should You Choose?
 https://xanderia.com/wp-content/uploads/2026/08/IMG-20260814-WA0191-e1787021591326.jpg
1442
2112
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-08-18 02:54:102026-08-18 03:50:39Perhimpunan Penjawat Awam dan Pelancaran Kibar Jalur Gemilang Peringkat Negeri Sembilan 2026
 https://xanderia.com/wp-content/uploads/2026/07/ChatGPT-Image-Jul-29-2026-04_10_27-PM-1.png
807
1949
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-07-31 08:37:152026-07-31 09:17:26Financial Literacy: Why Building an Emergency Fund Should Come Before Financing
 https://xanderia.com/wp-content/uploads/2026/03/WhatsApp-Image-2026-03-10-at-4.04.43-PM.jpeg
960
1280
Haryth Singularity
https://xanderia.com/wp-content/uploads/2025/12/Xanderia-NewLogo-300x300.png
Haryth Singularity2026-03-14 08:58:582026-06-15 03:28:41Kembara Prihatin Negeri Sembilan: Xanderia Menyantuni Penjawat Awam Sempena Bulan Ramadhan